BLS Jobs Report Collapses to 29K as August Revised Lower, PCE Inflation Improves, 10-Year Treasury Closes Beneath 5.29 Cautiously Floating
The BLS delivered just 29,000 jobs in September (vs. 90K expected), with August revised lower and July revised to -10K. PCE inflation improved on the portfolio management fee fix. Strong Treasury auctions showed investor appetite at generational high yields. France's fiscal crisis and Iran tensions remain headwinds. The 10-year closed beneath the critical 5.29 ceiling.
30-Year Fixed
6.875%
15-Year Fixed
6.625%
Where We Are Now
The BLS September jobs report was a disaster: only 29,000 jobs vs. 90K expected, with August's 162K revised lower as predicted and July revised to -10,000 (actual job losses). The birth/death model decreased the overall number, indicating small businesses are struggling. Jobs came almost entirely from leisure/hospitality (10K) and non-economically sensitive education/healthcare (20K); without those, it would have been job losses again. The household survey showed unemployment ticking up from 4.1% to 4.2%, driven by more people entering the labor force. Average hourly earnings decelerated from 3.1% to 3.0% YoY at $38/hr, and weekly earnings rose just 3.6% YoY to $1,300 - confirming no wage pressure inflation. Part-time jobs outweighed full-time, indicating less desirable employment growth. ADP data showed ~24K jobs/week over four weeks (~100K/month pace), consistent with the weak BLS number. Initial jobless claims remained extremely muted at 197K. The ISM services inflation component came in at its highest since July 2022, triggering a midweek lock alert, and consumer inflation expectations rose to 3.9% (highest since 2023), though the latter may reflect media bias rather than actual conditions.
New Home Sales
Cotality home price index for August. MBA data reflects weekly applications. CNBC survey shows 87% of renters want to own but many believe they need 20% down.
Inflation & Oil Pressure
PCE data reflects BEA portfolio management fee adjustment implemented Sept 30. Consumer expectations from NY Fed survey. ISM services inflation component triggered midweek lock alert.
30-Year Fixed
6.875%
15-Year Fixed
6.625%
10-Year Treasury
~5.25%
Inventory
4.3 months
MBS Technical Update, Week of October 12, 2026
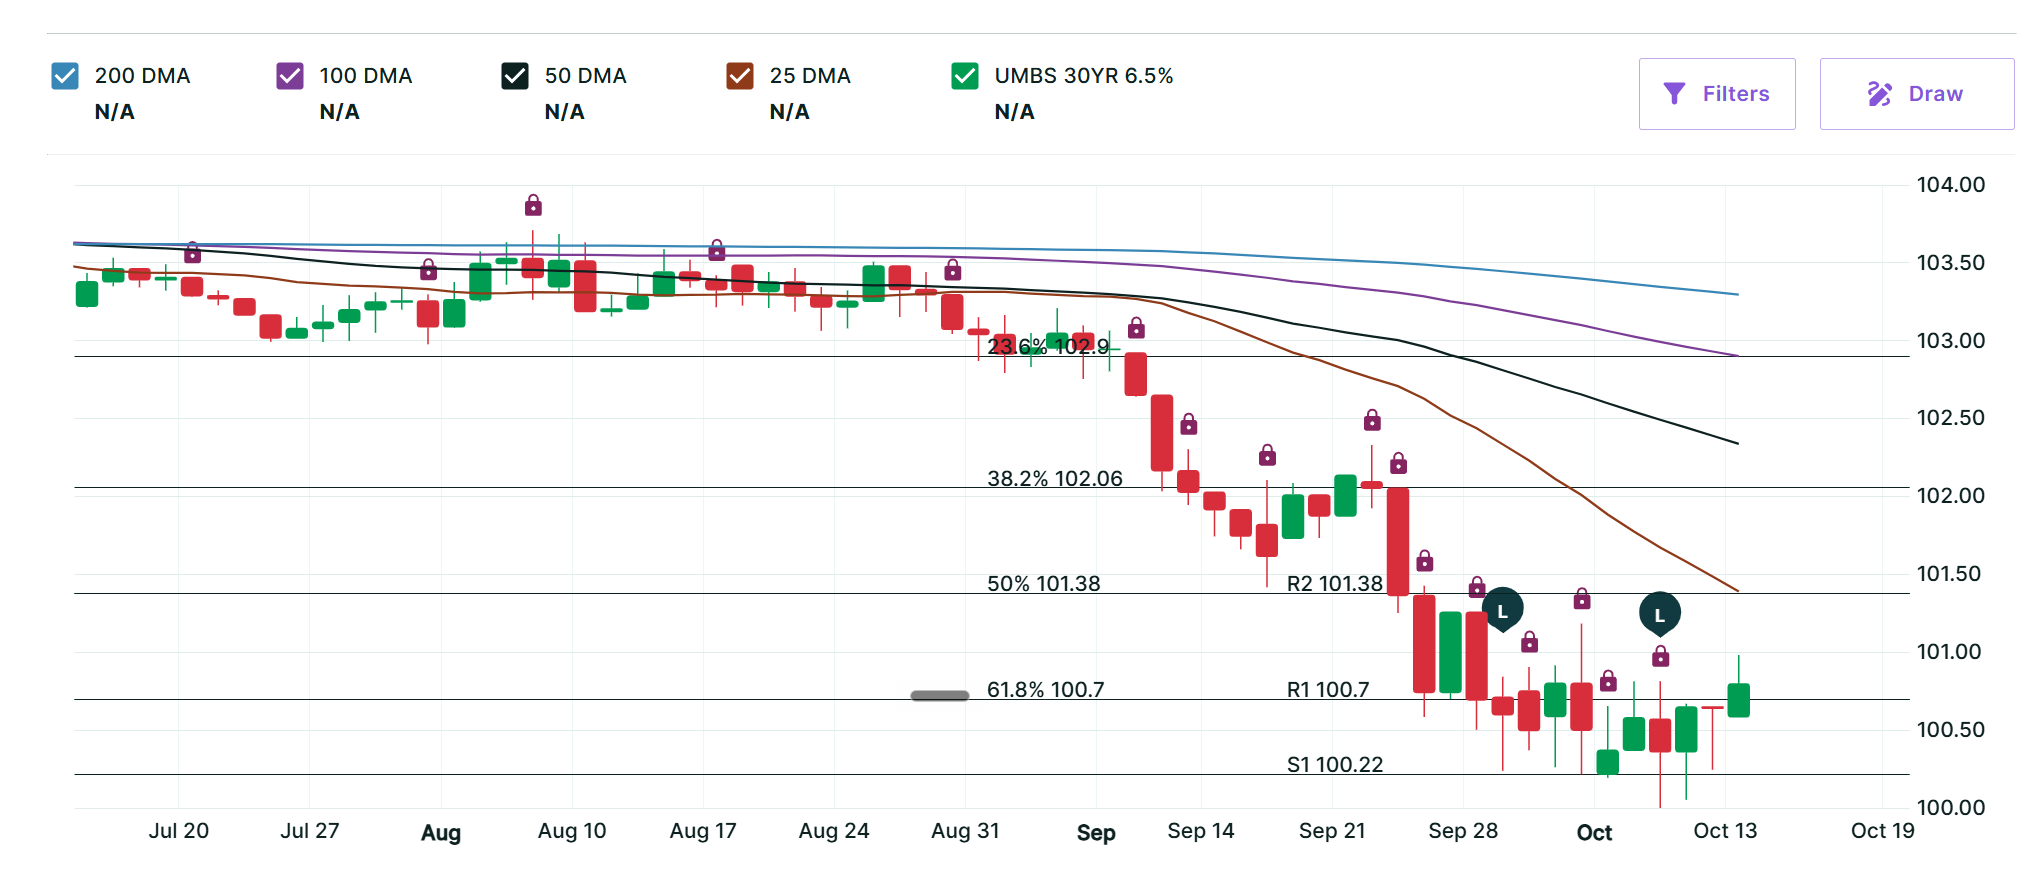
The week opened with a much-needed relief rally as the BLS September jobs report collapsed to just 29,000 (vs. 90K expected), with August's 162K revised lower and July revised to -10,000 (actual job losses). MBS surged 33 bps on Friday, breaking back above the Fibonacci level, and the 10-year Treasury dropped from its 5.34 peak back under the critical 5.29 ceiling (June 2007 highs). However, gains proved difficult to hold. France became a major headwind: their debt-to-GDP is 120%, the EU shot down both QE and a bond-buying rescue, and French oat yields surged, dragging global yields higher. A strong 10-year and 30-year Treasury auction midweek showed that the cure for higher yields may indeed be higher yields, as investors finally found bonds attractive at generational highs. By Thursday, the 10-year closed convincingly beneath 5.29 at ~5.25, and MBS held the 100.22 floor while testing 100.70 resistance. Trump signaled no Iran strike before midterms, providing de-escalation, but Hurricane Isaias shut in 1.3M barrels of Gulf oil. Fed minutes revealed a unanimous hike with most members expecting another by year-end, but weak jobs and improved PCE have made an October 28 hike unlikely. Chris Waller flip-flopped again, wanting more hikes but not consecutive. Next week is quiet on news (Monday closed for Columbus Day), so technicals will drive trading. CPI drops Wednesday, PPI Thursday.
MBS Floor
100.22
Held this floor throughout the week. Bounced off it multiple times. If it breaks, next support is 99.86 (Fibonacci level)
MBS Resistance
100.70
Currently testing this ceiling. If it breaks through, room to improve toward 101.38. Fibonacci level has been a pesky barrier
10-Yr Treasury
~5.25%
Closed convincingly beneath the 5.29 ceiling (June 2007 highs) on Thursday after battling it for 10 sessions. Next support at 5.16, resistance at 5.43 (2002 highs)
Oil (WTI)
~$92/bbl
Up from $89 on Trump's Iran comments (no deal, asked Pentagon for strike options). Hurricane Isaias shutting in 1.3M barrels of Gulf production. Still elevated
What Improved
- • BLS September: only 29,000 jobs (vs. 90K expected)
- • August BLS 162K revised lower (outlier confirmed as predicted)
- • July BLS revised to -10,000 (actual job losses)
- • Birth/death model decreased overall number (small businesses struggling)
- • Jobs came mostly from leisure/hospitality (10K) and education/healthcare (20K)
- • Unemployment ticked up from 4.1% to 4.2%
- • Avg hourly earnings: $38/hr, decelerated from 3.1% to 3.0% YoY
- • Weekly earnings: $1,300, up 3.6% YoY (no wage pressure inflation)
- • Hours worked unchanged at 34.4
- • Part-time jobs outweighed full-time (less desirable jobs)
- • PCE portfolio management fee fix finally implemented
- • PCE core YoY: 3.0% (vs. 3.3% expected)
- • Oil dropped to $89 on IEA proposal to release 50M barrels
- • France contemplating 50M barrels of diesel release
- • MBS relief rally: up 33 bps on weak jobs report (Friday)
- • Broke back above Fibonacci level on Friday
- • Stochastics showing early positive crossover signals
- • 10-year dropped from 5.34 peak back under 5.29 ceiling
- • Strong 10-year Treasury auction midweek (good buying at higher yields)
- • Stronger than average 30-year bond auction Thursday
- • "Cure for higher yields is higher yields" - investor appetite at generational highs
- • TINA reversed: bonds now attractive at multi-decade high yields
- • Trump signaled no Iran strike before midterms (de-escalation)
- • Fed speakers turning dovish: Jefferson, Bowman, Williams want to hold
- • John Williams: no urgency for October 28 hike
- • October 28 rate hike now unlikely after weak jobs and improved PCE
- • Chris Waller: wants more hikes but not consecutive (ok skipping Oct 28)
- • 10-year closed convincingly beneath 5.29 on Thursday
- • MBS held the 100.22 floor throughout the week
- • ADP: ~24K jobs/week over 4 weeks (~100K/month pace)
- • Cotality home prices: up 1.8% YoY (acceleration from 1.6%)
- • CNBC survey: 87% of renters want to own a home
- • Initial jobless claims: 197K (firing still extremely muted)
What to Watch
Next week: Monday closed (Columbus Day). Tuesday: existing home sales 10am + CPI preview. Wednesday: CPI released. Thursday: PPI. Quiet news week otherwise, so technicals and geopolitics will drive trading. Watch the 5.29 ceiling on the 10-year and 100.70 resistance on MBS.
- • France: debt/GDP 120% (double EU limit), under excessive deficit procedure
- • ECB shot down both QE and bond-buying rescue for France
- • French oat vs German bund spread widened to ~140 bps
- • France's debt cost expected to rise 59% by 2030
- • Global yields rising (German bund +11bps, French oats +14bps in 2 days)
- • Gains difficult to hold - relief rallies keep evaporating intraday
- • ISM services inflation component: highest since July 2022 (triggered lock alert)
- • Consumer inflation expectations rose to 3.9% (highest since 2023)
- • Fed minutes: unanimous hike, most expect another by year-end
- • Several Fed members want higher Fed funds for risk management
- • Chris Waller flip-flopping: wants more hikes but timing uncertain
- • Lori Logan: called for 50bp more, thinks job market strengthening
- • Kashkari: hike this year and another in 2027
- • Oil up to $92 on Trump's Iran comments (no deal, strike options requested)
- • Hurricane Isaias shutting in 1.3M barrels of Gulf oil production
- • September average gas price: $4.33/gallon (highest September average)
- • S&P near all-time highs, Nasdaq at all-time highs (narrow breadth)
- • Only 41% of stocks above 200 DMA, half in bear market territory
- • AI tech sector concentration creates vulnerability to sharp correction
- • MBA: rates up to 7.5%, purchases down 15% YoY, refis down 50%+ YoY
- • ARM share rising to 10-11% as borrowers seek alternatives
- • Cotality: home values down 0.1% MoM in August
- • 10-year: if closes above 5.29, next stop is 5.43 (2002 highs)
- • MBS: if 100.22 floor breaks, next support at 99.86
- • 30-year auction Thursday (30-year yields at multi-decade highs)
- • Flight to quality from France not benefiting U.S. bonds as expected
- • Potential selling in Japan or additional tech debt issuance as undercurrent
- • Carry trade unwinding risk could force selling of U.S. Treasuries
- • Ready for another reprice alert if gains don't hold
Current Stance: CAUTIOUSLY FLOATING - 10-YEAR BENEATH 5.29, MBS HOLDING 100.22 FLOOR, STRONG AUCTIONS, WATCHING CPI WEDNESDAYThe week opened with a relief rally on the weak BLS jobs report (29K vs. 90K expected), with August revised lower and July revised to -10K. MBS surged 33 bps Friday and broke above the Fibonacci level. However, gains were difficult to hold as France's fiscal crisis (debt/GDP 120%, ECB rescue shot down) dragged global yields higher. Midweek brought strong 10-year and 30-year Treasury auctions, confirming that higher yields are attracting buyers at generational highs. By Thursday, the 10-year closed convincingly beneath the critical 5.29 ceiling at ~5.25, and MBS held the 100.22 floor while testing 100.70 resistance. Trump's signal of no Iran strike before midterms provided de-escalation, though Hurricane Isaias shut in 1.3M barrels of Gulf oil. Fed minutes showed a unanimous hike with most expecting another by year-end, but weak jobs and improved PCE make October 28 unlikely. Next week is quiet on news (Columbus Day Monday, CPI Wednesday, PPI Thursday), so technicals will dominate. We're cautiously floating, watching whether the 10-year holds under 5.29 and MBS can break through 100.70.
The Trend: One Thing Leads to Another
The week was a technical tug-of-war. Friday's weak jobs report sparked a 33 bps MBS relief rally, breaking back above the Fibonacci level, and the 10-year dropped from its 5.34 peak back under the critical 5.29 ceiling (June 2007 highs). However, gains proved difficult to hold as France's fiscal crisis (debt/GDP 120%, ECB rescue shot down) dragged global yields higher. The French oat vs German bund spread widened to ~140 bps, and both German and French yields rose midweek. A strong 10-year auction Wednesday and stronger-than-average 30-year auction Thursday confirmed that higher yields are attracting buyers - the cure for higher yields may indeed be higher yields. The TINA acronym has reversed: with bonds at generational high yields, investors are finally finding them attractive. By Thursday, the 10-year closed convincingly beneath 5.29 at ~5.25, and MBS held the 100.22 floor while testing 100.70 resistance. The market is in the middle of a wide range and susceptible to whipsaws. Trump's signal of no Iran strike before midterms provided de-escalation, but Hurricane Isaias shut in 1.3M barrels of Gulf oil, pushing WTI back up to $92.
"The cure for higher yields is higher yields. For the first time, you can get a very attractive yield in the bond market, and savers and investors are starting to look at bonds as an attractive investment option."
Key Market Dynamics
BLS Jobs Collapse
September delivered just 29,000 jobs vs. 90K expected. August's 162K was revised lower as predicted, and July was revised to -10,000 (actual job losses). The birth/death model decreased the number, indicating small businesses struggling. Without leisure/hospitality and education/healthcare, it would have been job losses again.
France Fiscal Crisis
France's debt-to-GDP is 120% (double the EU limit), placing them under the excessive deficit procedure. The ECB shot down both QE and a bond-buying rescue. The French oat vs German bund spread widened to ~140 bps, and France's debt cost is expected to rise 59% by 2030. This is dragging global yields higher.
Strong Treasury Auctions
The 10-year auction Wednesday was strong, and the 30-year auction Thursday was stronger than average. With yields at multi-decade highs, investors finally find bonds attractive. The TINA acronym has reversed - bonds are now an appealing investment at generational high yields.
Fed Speaker Divide
Dovish camp: Jefferson, Bowman, and Williams want to hold and see more data; Williams signals no urgency for October 28. Hawkish camp: Logan wants 50bp more, Kashkari wants a hike this year and another in 2027. Waller flip-flopped again, wanting more hikes but not consecutive. Fed minutes showed unanimous hike with most expecting another by year-end.
Oil and Geopolitics
Oil dropped to $89 on the IEA's proposal to release 50M barrels, then rose back to $92 on Trump's Iran comments (no deal, asked Pentagon for strike options before midterms). Trump later signaled no strike before midterms. Hurricane Isaias is shutting in 1.3M barrels of Gulf oil production. September average gas price was $4.33/gallon.
Stock Market Concentration
The S&P 500 is near all-time highs and the Nasdaq set a fresh all-time high, but breadth is poor: only 41% of stocks are above their 200 DMA and half are in bear market territory. AI tech sector concentration creates vulnerability to a sharp correction, which could benefit bonds.
Where We're Going
Next week is quiet on the news front, so technicals will dominate trading. Monday markets are closed for Columbus Day. Tuesday brings existing home sales at 10am Eastern plus a CPI preview. CPI is released Wednesday and PPI on Thursday. The key technical levels to watch: the 10-year Treasury must hold beneath the 5.29 ceiling (June 2007 highs) - if it does, there is room to improve toward 5.16. If it breaks above 5.29, the next stop is the 2002 highs at 5.43, which would be ugly. For MBS, the 100.22 floor has held firm, and the market is testing the 100.70 resistance ceiling. A break above 100.70 would open room toward 101.38. The strong Treasury auctions this week suggest that higher yields are attracting buyers, which could provide a floor. However, the France situation remains a significant headwind - if their yields continue to rise, global yields will follow. The Fed's October 28 meeting is now unlikely to result in a hike after weak jobs and improved PCE, but Fed speakers throughout the week could shift sentiment. Geopolitical risks (Iran, Middle East) remain ever-present and could change the tenor of the market at any time.
Positive Catalysts
- BLS September: only 29K jobs vs. 90K expected (weak labor market)
- August 162K revised lower, July revised to -10K (job losses)
- PCE core YoY: 3.0% (vs. 3.3% expected) on portfolio fee fix
- Avg hourly earnings decelerated to 3.0% YoY (no wage inflation)
- Unemployment ticked up from 4.1% to 4.2%
- MBS relief rally: up 33 bps on weak jobs report
- 10-year closed convincingly beneath 5.29 ceiling
- Strong 10-year and 30-year Treasury auctions
- Higher yields attracting investors at generational highs
- Trump signaled no Iran strike before midterms (de-escalation)
- Fed speakers turning dovish (Jefferson, Bowman, Williams)
- October 28 rate hike now unlikely
- Oil dropped to $89 on IEA 50M barrel release proposal
- MBS held the 100.22 floor throughout the week
- Stochastics showing early positive crossover signals
Risk Factors
- France: debt/GDP 120%, ECB rescue shot down, yields surging
- French oat vs German bund spread widened to ~140 bps
- Global yields rising (German bund +11bps, French oats +14bps in 2 days)
- Relief rallies keep evaporating intraday (gains hard to hold)
- ISM services inflation component: highest since July 2022
- Consumer inflation expectations rose to 3.9% (highest since 2023)
- Fed minutes: most expect another hike by year-end
- Chris Waller flip-flopping on hike timing
- Logan wants 50bp more, Kashkari wants hikes this year and 2027
- Oil up to $92 on Trump Iran comments and Hurricane Isaias
- 1.3M barrels of Gulf oil shut in by Hurricane Isaias
- September average gas price: $4.33/gallon (highest September)
- Stock market narrow breadth: only 41% above 200 DMA
- AI tech concentration creates vulnerability to sharp correction
- MBA: purchases down 15% YoY, refis down 50%+ YoY
- If 10-year closes above 5.29, next stop is 5.43 (2002 highs)
- If MBS breaks 100.22, next support at 99.86
- Potential selling in Japan or tech debt issuance as undercurrent
- Flight to quality from France not benefiting U.S. bonds as expected
Current Stance
CAUTIOUSLY FLOATING - MBS RELIEF RALLY ON WEAK JOBS, PCE INFLATION IMPROVED, OIL DOWN TO $89, OCTOBER FED HIKE UNLIKELY
Today's Rates
As of October 12, 2026, subject to change without notice
Rates are for informational purposes only and subject to change without notice. APR includes fees. Contact your loan officer for a personalized quote.
Bottom Line
The week ended on an improved footing after a much-needed relief rally. The BLS September jobs report collapsed to just 29,000 (vs. 90K expected), with August revised lower and July revised to -10,000 (actual job losses) - confirming that the labor market is not as strong as headline numbers suggested. PCE inflation improved meaningfully with the portfolio management fee fix. The 10-year Treasury closed convincingly beneath the critical 5.29 ceiling, and MBS held the 100.22 floor. Strong Treasury auctions confirmed investor appetite at generational high yields. However, France's fiscal crisis (debt/GDP 120%, ECB rescue shot down), Hurricane Isaias disrupting Gulf oil, and lingering inflation concerns (ISM services, consumer expectations) remain significant headwinds. Gains have been difficult to hold, and the market is in the middle of a wide range, susceptible to whipsaws. Next week's CPI and PPI data will be critical. We are cautiously floating, watching whether the 10-year holds under 5.29 and MBS can break through 100.70 resistance.
Get Started Today — 516-406-4940