BLS Jobs Report Surges to 162K But Conflicts with ADP and JOLTS as Oil Hits $93 Cautiously Floating
BLS delivers a surprise 162K jobs, but ADP at 38K and JOLTS at 7.27M tell a weaker story. All eyes turn to Friday's CPI report ahead of the September 16 Fed meeting. Oil surges to $93 on Middle East escalation.
30-Year Fixed
6.875%
15-Year Fixed
6.5%
Where We Are Now
The week opened with JOLTS at 7.27M job openings, but with a 177K downward revision to the previous report, net job openings fell by ~100K. The quit rate dropped to 1.9% (lowest since 2014) and the hire rate fell to 3.2% (just off lowest since 2013), signaling weakening labor demand. Tuesday's ADP report came in at just 38,000 jobs (vs. 53,000 estimate), the fewest in seven months, with all growth from large businesses in education and healthcare. Fed Gov Michael Barr echoed Warsh's hawkish tone, saying if inflation doesn't improve at CPI, the Fed should hike at September 16. NY Fed President John Williams struck a dovish tone, saying rates are "in a good place" and yields are rising because of a strong economy, not inflation. Thursday's BLS report delivered a surprise 162,000 jobs (vs. 58,000 estimate), but it conflicts sharply with ADP (38K) and Revelio (37K). The birth/death ratio added 74,000, leisure/hospitality surged 62,000 (vs. ADP's 16,000), and the household survey showed 569,000 job gains with full-time jobs up 735,000. Positive revisions totaled 55,000 (July revised from -23K to +21K). However, given the BLS track record and QCEW revisions, this may be an outlier. Norway's sovereign wealth fund proposed reducing Treasury holdings by ~$80B, adding selling pressure. Oil surged to $93/barrel after Iran attacked a U.S. aircraft carrier, the U.S. sunk three Iranian oil tankers, and Houthis attacked a Saudi oil refinery. Diesel prices hit an all-time high. Energy Secretary Chris Wright noted 17M barrels moved through the Strait of Hormuz (vs. 20M pre-war). MBA showed rates at ~6.8%, purchases flat, refis -19% YoY but still 42% of transactions. CoreLogic reported July home prices flat MoM, +1.4% YoY, with a 2% appreciation forecast for the next 12 months. All eyes now turn to Friday's CPI report ahead of the September 16 Fed meeting.
New Home Sales
Source: BLS, ADP, CoreLogic, MBA. BLS August: 162,000 jobs (vs. 58K estimate), 127,000 private (ex. 35K gov). Birth/death ratio added 74K. Positive revisions +55K (July from -23K to +21K). Household survey: 569K job gains, labor force +683K, full-time +735K, part-time -223K. ADP August: 38,000 (fewest in 7 months, est. 53K), all from large businesses (education/healthcare). JOLTS: 7.27M openings, 177K downward revision, quit rate 1.9% (lowest since 2014), hire rate 3.2% (just off lowest since 2013). Unemployment 4.1%. CoreLogic: July home prices flat MoM, +1.4% YoY, forecast 2% appreciation (up from 1.5%). MBA: rates ~6.8%, purchases flat, refis -19% YoY (42% of transactions).
Inflation & Oil Pressure
Source: BEA, BLS, EIA. CPI August (Friday): headline est. +0.4% MoM (3.4% YoY unchanged), core est. +0.2% MoM (YoY expected to drop from 2.5% to 2.4%). Fed funds futures: 58% chance of 25bp hike at September 16 meeting. Oil (WTI) ~$93/barrel on Middle East escalation (Iran attacked U.S. aircraft carrier, U.S. sunk 3 Iranian tankers, Houthis attacked Saudi refinery). Diesel at all-time high. 10-year Treasury ~4.76%. Global yields at highest in almost 20 years. Norway sovereign wealth fund proposed reducing Treasuries by ~$80B. Strait of Hormuz: 17M barrels/day (vs. 20M pre-war). Energy Secretary optimistic on Venezuelan oil ramp-up.
30-Year Fixed
6.875%
15-Year Fixed
6.5%
10-Year Treasury
~4.76%
Inventory
4.6 months months
MBS Technical Update, Week of September 8, 2026
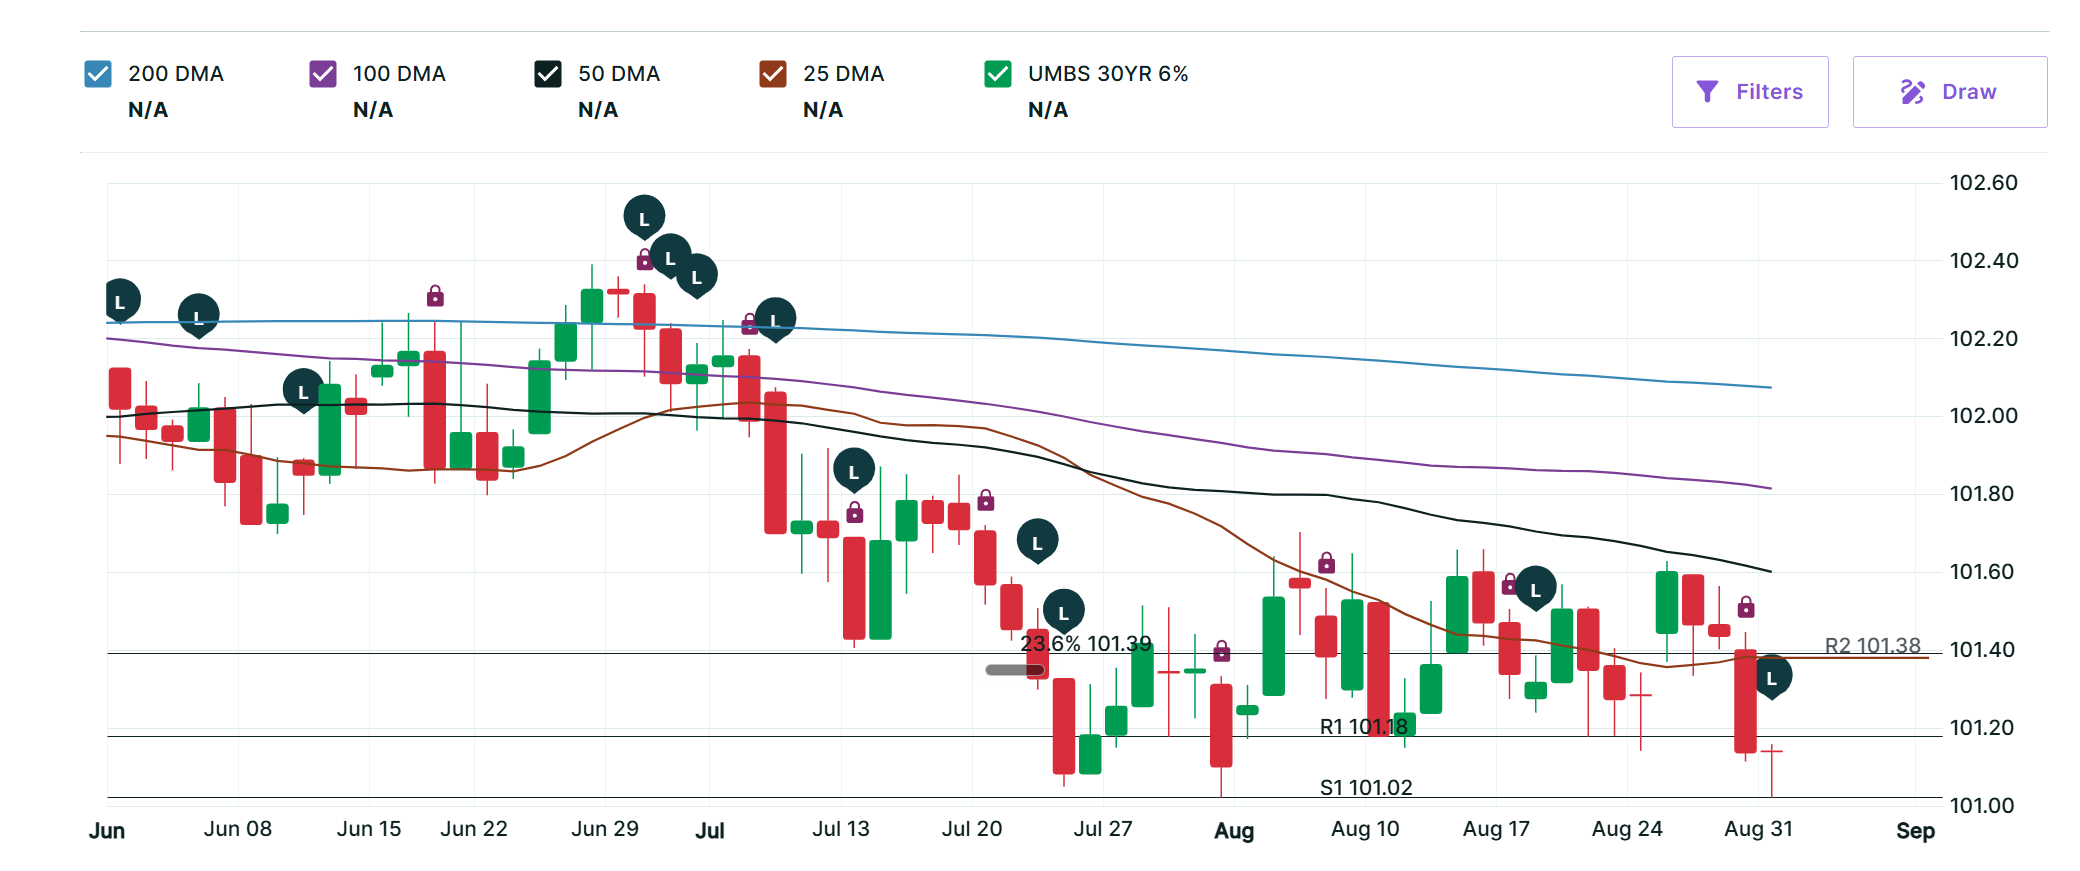
The week opened with JOLTS at 7.27M (weakest since 2014 by quit/hire rates), ADP at just 38K (fewest in 7 months), then Thursday's BLS delivered a surprise 162K jobs that conflicts sharply with ADP and Revelio. MBS dipped 15 bps on the BLS shocker but recovered to close up 6 bps on Sept 8. The 10-year Treasury broke above 4.71 to 4.76, testing the 4.81 ceiling (January 2025 levels). Oil surged to $93 on Middle East escalation. MBS is range-bound between 101.18 and 101.02 on weak support floors. All eyes now turn to Friday's CPI report ahead of the September 16 Fed meeting.
MBS Floor
101.02
Range-bound between 101.18 and 101.02. Support held all week but may not be strong. Could lose another 24 bps if it breaks
MBS Resistance
101.18
Top of the range. MBS up 6 bps on Sept 8, bouncing off support. Need to break above this to see improvement
10-Yr Treasury
~4.76%
Broke above 4.71 ceiling. Testing 4.81 resistance (January 2025 levels). Range-bound, waiting for CPI Friday
Oil (WTI)
~$93/bbl
Surging on Middle East escalation. Iran attacked U.S. carrier, U.S. sunk 3 Iranian tankers, Houthis attacked Saudi refinery. Diesel at all-time high
What Improved
- • MBS up 6 bps on Sept 8, bouncing off support floor
- • 10-year Treasury slightly lower at 4.76%
- • JOLTS weak report helped bonds recoup early losses
- • ADP at 38K (fewest in 7 months) confirms weak labor market
- • Quit rate at 1.9% (lowest since 2014) signals less job hopping
- • Hire rate at 3.2% (just off lowest since 2013)
- • John Williams dovish: rates "in a good place"
- • Energy Secretary: 17M barrels through Strait of Hormuz (vs 20M pre-war)
- • Oil briefly dropped under $90 on Sept 2 before surging back
- • CoreLogic home prices +1.4% YoY, forecast 2% appreciation (up from 1.5%)
- • MBA purchases flat (transactions still happening)
- • Refis still 42% of transactions
- • BLS positive revisions: +55K total (July revised from -23K to +21K)
- • Full-time jobs up 735K, part-time down 223K
- • Labor force increased 683K
- • 10-year ceiling at 4.81 tested but held
- • MBS support floor held throughout the week
- • Venezuelan oil ramp-up could help bring prices down
What to Watch
Next week: CPI report Friday (headline +0.4% MoM, core +0.2% MoM, YoY core expected to drop from 2.5% to 2.4%). September 16 Fed meeting - hike decision hinges on CPI. Also Thursday: PPI and existing home sales.
- • BLS surprise 162K jobs conflicts with ADP (38K) and Revelio (37K)
- • Fed futures now 58% chance of September hike (up from 48%)
- • Michael Barr hawkish: if CPI doesn't improve, Fed should hike
- • Oil at $93/barrel, diesel at all-time high
- • Iran attacked U.S. aircraft carrier, U.S. sunk 3 Iranian oil tankers
- • Houthis attacked Saudi oil refinery
- • Global bond sell-off, global yields at highest in almost 20 years
- • Norway sovereign wealth fund proposing to reduce Treasuries by ~$80B
- • 10-year Treasury at 4.76%, broke above 4.71 ceiling
- • MBS range-bound between 101.18 and 101.02, weak support floors
- • 10-year ceiling at 4.81 (going back to January 2025)
- • MBS could lose another 24 bps if support breaks
- • AI data center buildout causing corporate bond issuance competing with Treasuries
- • Birth/death ratio added 74K to BLS number (questionable)
- • BLS leisure/hospitality +62K vs ADP +16K (big disparity)
- • MBA refis -19% YoY
- • Rates at highest levels in over a year
- • CPI report Friday could determine Fed hike at Sept 16
- • Core CPI expected to drop from 2.5% to 2.4% but upside surprise puts hike on table
- • Lori Logan and Beth Hammack still think job market is strengthening
- • 700,000 people left labor force since May (why unemployment dropped)
- • QCEW revisions showed 30% downward revision last year
Current Stance: CAUTIOUSLY FLOATING, MBS AT SUPPORT FLOOR, 10-YR AT 4.76%, OIL AT $93/BBL, CPI FRIDAY WILL DETERMINE SEPT 16 FED DECISIONBLS delivered a surprise 162K jobs but ADP at 38K and JOLTS at 7.27M tell a weaker story. The bond market appears skeptical given the BLS track record of later downward revisions. Fed funds futures now pricing 58% chance of September hike. Michael Barr echoed Warsh's hawkish tone, while John Williams struck dovish. Oil surged to $93 on Middle East escalation (Iran attacked U.S. carrier, U.S. sunk 3 Iranian tankers, Houthis attacked Saudi refinery), diesel at all-time highs. Norway proposed $80B Treasury sell-off. 10-year at 4.76% testing 4.81 ceiling. MBS range-bound on weak support. All eyes on Friday's CPI report ahead of September 16 Fed meeting. We're floating but watching CPI and technical levels closely.
The Trend: One Thing Leads to Another
The week was dominated by conflicting jobs data and rising oil prices. Monday's JOLTS report showed 7.27M job openings, but with a 177K downward revision, net openings fell ~100K. The quit rate at 1.9% (lowest since 2014) and hire rate at 3.2% (just off lowest since 2013) confirm weakening labor demand. Tuesday's ADP came in at just 38,000 (vs. 53,000 estimate), the fewest in seven months, with all growth from large businesses in education and healthcare - not economically sensitive sectors. Fed Gov Michael Barr echoed Warsh, saying if inflation doesn't improve at CPI, the Fed should hike on September 16. However, NY Fed President John Williams struck a dovish tone, saying rates are "in a good place" and yields are rising because of a strong economy, not inflation. He attributed the growth to AI data center buildout and competing corporate bond issuance. Energy Secretary Chris Wright noted 17M barrels moved through the Strait of Hormuz (vs. 20M pre-war) and was optimistic on Venezuelan oil ramp-up. Thursday's BLS report was a shocker: 162,000 jobs vs. 58,000 estimate, with 35,000 government and 127,000 private. The birth/death ratio added 74,000, leisure/hospitality surged 62,000 (vs. ADP's 16,000), and the household survey showed 569,000 job gains with full-time jobs up 735,000. Positive revisions totaled 55,000 (July revised from -23K to +21K). However, this sharply conflicts with ADP (38K) and Revelio (37K), and given the BLS track record of later downward revisions, the bond market appears skeptical. Norway's sovereign wealth fund proposed reducing Treasury holdings by ~$80B, adding selling pressure. Oil surged to $93/barrel on Middle East escalation, with diesel at all-time highs. The bond market would respond well to a hike, but it would damage an already weak economy.
"Many Fed members are counting on the job market stability. Some even saying that it's strengthening, but when you look deeper at the numbers, it's just an illusion."
Key Market Dynamics
BLS Jobs Report Surges but Conflicts with ADP/JOLTS
Thursday's BLS report delivered a surprise 162,000 jobs (vs. 58,000 estimate), with 35,000 government and 127,000 private. The birth/death ratio added 74,000, leisure/hospitality surged 62,000 (vs. ADP's 16,000), and the household survey showed 569,000 job gains with full-time jobs up 735,000. Positive revisions totaled 55,000 (July revised from -23K to +21K). However, this conflicts sharply with ADP (38K) and Revelio (37K), and given the BLS track record of later downward revisions (QCEW showed 30% downward revision last year), the bond market appears skeptical. August is typically a high month for later downward revisions.
Fed Members Divided: Barr Hawkish, Williams Dovish
Fed Gov Michael Barr echoed Warsh's hawkish tone from Jackson Hole, saying if inflation doesn't improve at next week's CPI report ahead of the September 16 meeting, the Fed should hike. However, NY Fed President John Williams struck a dovish tone, saying rates are "in a good place" and yields are rising because of a strong economy, not inflation. He attributed the growth to AI data center buildout causing corporate bond issuance that competes with Treasuries. Williams is very influential as Fed operations run through the New York Fed. Lori Logan and Beth Hammack still think the job market is strengthening, despite the weak data. Fed funds futures now price a 58% chance of a 25bp hike at September 16.
Oil Surges to $93 on Middle East Escalation
Oil surged to $93/barrel after a dramatic weekend of escalation: Iran attempted an attack on a U.S. aircraft carrier, the U.S. sunk three Iranian oil tankers, and Houthis attacked a major Saudi Arabian oil refinery. Diesel prices hit an all-time high, which affects 99% of land freight. The global bond sell-off continued with global yields at their highest levels in almost 20 years. Energy Secretary Chris Wright noted 17M barrels moved through the Strait of Hormuz on Monday (vs. 20M pre-war) and was optimistic on Venezuelan oil ramp-up, but any relief remains elusive.
JOLTS Reveals Weakening Labor Market
JOLTS came in at 7.27M job openings, but with a 177K downward revision to the previous report, net job openings fell by ~100K. The quit rate dropped from 2% to 1.9% (lowest since 2014), signaling fewer workers are voluntarily leaving jobs. The hire rate dropped from 3.4% to 3.2% (just off the lowest since 2013), confirming lackluster hiring. Additionally, about 1/5 of job openings may not be real (window dressing), and double counting occurs at the state level with work-from-anywhere positions. The low unemployment rate of 4.1% masks the weakness, as 700,000 people have left the labor force since May.
Norway Proposes $80B Treasury Sell-off
Norway's sovereign wealth fund, the world's largest, announced a proposal to reduce Treasury holdings by about $80 billion. This selling pressure could be another headwind for lower yields. However, it's just a proposal for now, and it's unclear what the breakdown of those Treasuries would be or whether the funds would be reinvested into mortgage-backed securities. This adds to existing pressure from AI-related corporate debt issuance competing for bond market liquidity.
Where We're Going
All eyes now turn to Friday's CPI report for August, which will likely determine whether the Fed hikes at the September 16 meeting. Expectations are for headline CPI +0.4% MoM (3.4% YoY, unchanged) and core CPI +0.2% MoM, with the year-over-year core expected to tick down from 2.5% to 2.4%. If core decelerates as expected, the Fed likely remains on hold. However, any upside surprise puts a hike firmly on the table. Fed funds futures currently price a 58% chance of a 25bp hike. The BLS jobs report's 162K figure conflicts sharply with ADP (38K) and Revelio (37K), and given the BLS track record of later downward revisions, the bond market may not be taking it at face value. Oil at $93/barrel and diesel at all-time highs remain significant headwinds, with Middle East escalation showing no signs of abating. Norway's proposed $80B Treasury sell-off adds another layer of pressure. The 10-year Treasury is range-bound between support and the 4.81 ceiling, while MBS sits on a support floor that has held but may not be strong. We are floating but watching CPI closely.
Positive Catalysts
- MBS up 6 bps on Sept 8, bouncing off support floor
- 10-year Treasury slightly lower at 4.76%
- JOLTS weak report helped bonds recoup early losses
- ADP at 38K (fewest in 7 months) confirms weak labor market
- Quit rate at 1.9% (lowest since 2014) signals less job hopping
- Hire rate at 3.2% (just off lowest since 2013)
- John Williams dovish: rates "in a good place"
- Energy Secretary: 17M barrels through Strait of Hormuz (vs 20M pre-war)
- Oil briefly dropped under $90 on Sept 2 before surging back
- CoreLogic home prices +1.4% YoY, forecast 2% appreciation (up from 1.5%)
- MBA purchases flat (transactions still happening)
- Refis still 42% of transactions
- BLS positive revisions: +55K total (July revised from -23K to +21K)
- Full-time jobs up 735K, part-time down 223K
- Labor force increased 683K
- 10-year ceiling at 4.81 tested but held
- MBS support floor held throughout the week
- Venezuelan oil ramp-up could help bring prices down
Risk Factors
- BLS surprise 162K jobs conflicts with ADP (38K) and Revelio (37K)
- Fed futures now 58% chance of September hike (up from 48%)
- Michael Barr hawkish: if CPI doesn't improve, Fed should hike
- Oil at $93/barrel, diesel at all-time high
- Iran attacked U.S. aircraft carrier, U.S. sunk 3 Iranian oil tankers
- Houthis attacked Saudi oil refinery
- Global bond sell-off, global yields at highest in almost 20 years
- Norway sovereign wealth fund proposing to reduce Treasuries by ~$80B
- 10-year Treasury at 4.76%, broke above 4.71 ceiling
- MBS range-bound between 101.18 and 101.02, weak support floors
- 10-year ceiling at 4.81 (going back to January 2025)
- MBS could lose another 24 bps if support breaks
- AI data center buildout causing corporate bond issuance competing with Treasuries
- Birth/death ratio added 74K to BLS number (questionable)
- BLS leisure/hospitality +62K vs ADP +16K (big disparity)
- MBA refis -19% YoY
- Rates at highest levels in over a year
- CPI report Friday could determine Fed hike at Sept 16
- Core CPI expected to drop from 2.5% to 2.4% but upside surprise puts hike on table
Current Stance
CAUTIOUSLY FLOATING - MBS AT SUPPORT FLOOR, 10-YR AT 4.76%, OIL AT $93/BBL, CPI FRIDAY WILL DETERMINE SEPT 16 FED DECISION
Today's Rates
As of September 8, 2026, subject to change without notice
Rates are for informational purposes only and subject to change without notice. APR includes fees. Contact your loan officer for a personalized quote.
Bottom Line
MBS opened the week near flat, dipped on the surprise 162K BLS jobs report (down 15 bps on Sept 4), but recovered to close slightly positive on Sept 8 (up 6 bps). The BLS number conflicts with weaker ADP (38K) and JOLTS data, and the bond market appears skeptical given the BLS track record of later downward revisions. All eyes now turn to Friday's CPI report, which will likely determine the Fed's September 16 decision. Fed futures price a 58% chance of a hike. Oil surged to $93 on Middle East escalation (Iran attacked U.S. aircraft carrier, U.S. sunk 3 Iranian tankers, Houthis attacked Saudi refinery), with diesel at all-time highs. Norway's sovereign wealth fund proposed reducing Treasuries by ~$80B. We are cautiously floating, watching CPI and technical levels closely.